
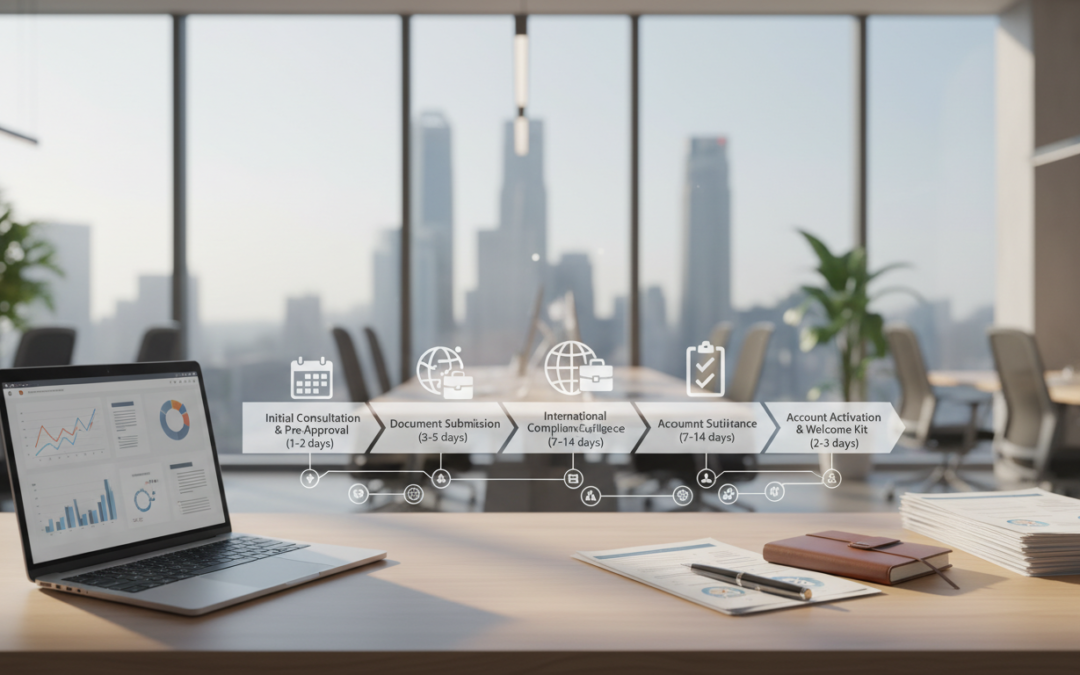
Did you know that many non-resident founders should plan a 4–8 week window when seeking a corporate bank account in Singapore due to enhanced compliance checks?
Traditional banks often take longer because of extra diligence, while digital providers can onboard faster if risk and verification lines up.
This short guide sets a realistic expectation of approval time and explains why overseas founders face deeper scrutiny.
It is aimed at non-resident directors, overseas shareholders and newly incorporated entities who need a clear, stage-by-stage path from incorporation and UEN readiness to activation and early monitoring.
Practical tip: prepare complete documents, keep a consistent business narrative and reply promptly to queries to get approved faster — or consider starting with a digital provider and adding a traditional provider later for credit and trade finance.
Key Takeaways
- Expect approximately 4–8 weeks with traditional banks; fintechs may be quicker.
- Enhanced diligence explains longer processing for non-resident founders.
- Be ready with clear documents and a consistent business story to speed approval.
- Decide early: start with a digital provider or pursue a full-service option later.
- Follow the stage-by-stage breakdown in this guide for predictable progress.
- For tailored package options, see our quick resources at service packages.
Why a corporate bank account in Singapore is essential for foreign-owned companies
A local corporate banking relationship is often the practical backbone that keeps day-to-day operations running smoothly.
Payments, payroll and supplier transactions
Using a dedicated corporate account helps receive customer payments, settle supplier invoices and run payroll without friction.
Counterparties in Singapore expect proper channels; this reduces delays and supports fast reconciliation.
Supporting tax filings and regulatory obligations
Clear records make IRAS reporting and audits much easier. Good statements show income, expenses and GST flows.
Access to trade finance and business credit
As operations grow, a persistent banking relationship can unlock trade finance, credit lines and other services tied to turnover history.
Legal separation and credibility
Separating personal and business money protects directors and improves trust with partners and investors.
“A local corporate relationship signals genuine operational presence and reduces questions about substance.”
Note: banks will review intended usage, volumes and counterparties. Clear purpose and documents reduce follow-up and speed approval in Singapore’s strict compliance environment.
How long it really takes in Singapore today and why foreign founders face delays
Many founders are surprised that verification often stretches into multiple weeks once scheduling and follow-ups are counted.
Real-world approval windows separate two parts: appointment lead time and internal review. Appointment slots at traditional banks can add one to three weeks before any compliance work starts.
Internal review then follows. Typical end-to-end processing with established lenders runs about 4–8 weeks, while digital providers may finish in days to 1–3 weeks if risk scoring is low.
Why AML and KYC take longer
Enhanced AML and KYC demand deeper UBO checks, broad screening and clear source-of-funds evidence. This extra due diligence is routine on non-local structures.
Limited access to overseas registries and inconsistent documents increases verification queries. Banks request certified translations, notarised copies and extra references, which creates cycles of clarifications.
Practical points to plan cashflow
- Separate appointment delay from internal review when planning cash needs.
- Prepare robust source-of-wealth papers to reduce back-and-forth.
- Consider applying to a digital provider alongside a traditional lender to hedge timing risk.
Next: a stage-by-stage breakdown will show where your specific bottleneck usually occurs and how to address it proactively.
Bank account opening timeline for foreign owned Singapore company: stage-by-stage breakdown
Break the process into clear stages so founders can map dates to milestones rather than guess.
1. Incorporation and UEN
Start with incorporation at ACRA and secure a UEN. Banks will not assess an application without core ACRA records and the official UEN.
2. Document collation
Collect current passports, proof of address, board minutes and business evidence. Expect paperwork to be valid within 1–3 months to avoid re-submissions.
3. Appointment lead times
Traditional lenders such as DBS, OCBC and UOB often require 1–4 weeks to schedule meetings. Lead times vary with demand and case complexity.
4. Compliance review and approval
Internal checks include KYC screening, UBO verification, source-of-wealth and a formal risk assessment. This stage commonly takes 1–4+ weeks before approval.
5. Activation and setup
Once approved, perform the initial deposit, authorise signatories and enable internet banking. Test payment rails before live operations.
Plan conservatively: work backwards from any fixed funding date and allow buffer days at each stage.
Pre-application prerequisites banks require before they assess your account opening
Before any application is assessed, banks will expect core corporate steps to be complete and verifiable.
Incorporation must be completed first
Incorporation and a valid UEN are non-negotiable. Lenders will not start a formal review without official registry outputs.
Missing or incomplete ACRA records cause immediate delays. If documents are amended after submission, expect fresh checks and extra requests.
Local representative and resident director considerations
Resident directors or local representatives can reduce perceived risk. Structures controlled only by non-resident stakeholders typically trigger deeper scrutiny.
When non-resident control exists, banks increase due diligence and may require additional proofs of substance.
Board authorisation and signatories
Provide a clear board resolution that names who may sign, their signing rules and transaction limits. This shows governance and avoids on-the-spot queries.
- Non-negotiables: incorporated entity, UEN, decision-making authority, identifiable signatories.
- Ensure signatory names match passports and corporate registers exactly.
- Confirm travel availability if in-person verification is required and have originals ready.
When these requirements and documentation are prepared up front, the reviewer has fewer reasons to pause. That reduces back-and-forth and keeps applications moving smoothly.
Document checklist for foreign-owned companies opening bank accounts Singapore-wide
A clear, consistent documentation pack is the single best way to reduce delays during the verification phase.
Core corporate paperwork
Provide the ACRA Business Profile, Constitution, registers and a board resolution that authorises the corporate bank account.
Identity and address proofs
Include passport copies and recent proof of residential address for all directors, shareholders and UBOs. Use consistent formats and certified copies if requested.
Evidence of business activities
Show a working website, signed contracts, invoices or platform screenshots. These help banks verify commercial purpose and expected transaction corridors.
Financial disclosures and administrative accelerators
Declare source of funds with supporting trails and realistic projected monthly volumes and counterparty countries.
Prepare CorpPass access or MyInfo Business-style verification to speed checks.
“Consistency across names, dates and addresses prevents many common compliance delays.”
| Item | Typical requirement | Why it matters |
|---|---|---|
| ACRA Business Profile | Recent copy (within 3 months) | Confirms legal status and UEN |
| Board resolution | Signed minute naming signatories | Shows authority to open a corporate bank account |
| KYC documents | Passport + proof of address | Identifies directors, shareholders and UBOs |
| Business evidence | Website, contracts, invoices | Verifies activities and expected transactions |
| Financial disclosures | Source of funds + projected volumes | Support risk assessment and monitoring |
Notarisation, apostille, and certified translations for overseas documents
Proofs issued overseas often need legalisation before local reviewers will accept them. Get this right early to avoid last-minute rejections and repeated checks.
When apostille applies versus consular legalisation
If a country is a Hague Apostille Convention signatory, an apostille usually suffices. If not, you will need consular legalisation from the destination embassy.
Which documents commonly trigger notarisation
Identity papers, proof of address and foreign corporate extracts often require notarisation and subsequent legalisation. These are the items that typically slow due diligence.
Handling non-English papers
Obtain certified English translations and keep originals with the translated copies. Submit both sets to meet documentation requirements and reduce follow-up queries.
Standardise names, dates and addresses
Ensure identical spelling across passports, utility bills and company registers. Use consistent date formats and matching addresses to cut friction in checks and compliance.
- Audit names, dates and addresses before submission.
- Include original and certified translation together.
- Confirm whether an apostille or consular stamp is needed.
| Document | Typical need | Why it matters |
|---|---|---|
| Passport / ID | Notarised copy + legalisation | Identity verification during due diligence |
| Utility bill | Recent original | Proof of address; must match other records |
| Foreign corporate extract | Notarised + apostille/consular | Confirms legal status and UBO data for the corporate bank account |
Choosing the right bank account Singapore option for your business model
Your choice of provider should be driven by expected transaction patterns, not brand recognition.
Traditional providers such as DBS, OCBC, UOB and Standard Chartered suit businesses that need wide services and credit lines. They offer trade finance and lending once a relationship is established.
Digital providers like Aspire, Airwallex and Wise Business onboard faster and handle remote teams well. They often limit volumes and expect clear cross-border flows.
Key comparison points
- Model fit: trading and e‑commerce need payment rails; SaaS needs multi‑currency receipts.
- Multi‑currency: hold USD/EUR balances, check FX spreads and transfer pricing.
- Costs: compare minimum deposit, monthly fees and transaction charges carefully.
| Type | Best for | Trade credit |
|---|---|---|
| Traditional banks | Established operations | Available |
| Digital providers | Early‑stage & remote teams | Limited |
Practical approach: start with a digital setup to move money quickly, then add a traditional corporate bank account when you can support in‑person checks and higher volumes.
Physical presence versus remote onboarding: what to expect from banks
Physical presence requirements often shape the practical plan for onboarding and travel. Traditional providers typically insist that at least one director or authorised signatory attends a branch for an interview and original ID sighting. That visit usually covers document verification and a short business discussion.
In-person interviews and original document checks at traditional banks
Expect a branch interview to include ID checks, signature verification and questions about customers and cash flows. Bring certified originals and board minutes if asked.
Tip: plan 1–2 working days on site to allow for any immediate follow-ups.
Video KYC and fully remote options with digital providers
Some lenders and fintechs offer video KYC. Availability differs by risk profile and local policy, so remote approval is not guaranteed.
Digital providers can often onboard faster, but they still run the same KYC and AML checks. Provide clear proof of business activity to avoid delays with video verification.
How to plan travel timelines around appointment lead times
Appointment lead times commonly range 1–4 weeks. This scheduling element often adds more delay than the internal review itself.
- Align flights to confirmed slots and keep flexibility in your return date.
- Allow buffers for follow-up documents and rechecks.
- Submit one application to a remote-friendly provider as contingency if travel is uncertain.
| Check | Typical requirement | Practical plan |
|---|---|---|
| In-person interview | Director or authorised signatory present | Book 1–2 days; bring originals |
| Video KYC | Live ID check + proof of business | Confirm provider supports video; send documents early |
| Appointment lead time | 1–4 weeks | Book early and align travel |
Contingency advice: if travel is risky, apply to at least one remote‑friendly provider while you pursue traditional channels. Preparation speeds approval regardless of channel. For extra guidance on cross-border applications, see our recommended resource at opening a business bank account as a.
How to prepare a bank-ready business profile that passes due diligence
Prepare a concise business narrative that lets reviewers quickly understand what you sell and how money flows. Keep it factual, specific and tied to real evidence to minimise queries and speed approval.
Describe activities clearly
List what you sell, who buys it and which channels you use. Avoid vague phrases; state product names, pricing models and delivery methods.
Map expected transactions
Provide typical invoice size, monthly frequency, main counterparties and the countries where funds move. Include examples of recent payments or projected volumes.
Why choose Singapore
Explain operational rationale: regional hub, client access, hiring plans or supplier base. Tie the choice to tangible actions such as a leased office, local staff or signed regional contracts.
Supporting proof
- Signed contracts, invoices and customer agreements.
- Active website pages, proposals and vendor terms.
- Corporate presentations showing revenue model.
One-page summary
Include: business model, ownership, key customers, countries, payment flows and projected volumes. A single page reduces follow-up and helps compliance reviewers make quick decisions.
| Section | What to include |
|---|---|
| Business model | Products, pricing, channels |
| Transactions | Invoice size, frequency, corridors |
| Proof | Contracts, invoices, website links |
Step-by-step account opening process from application to approval
A clear, stepwise plan helps teams move from application submission to final approval without surprise delays.
Submitting applications and booking meetings
Start by preparing a single, consistent pack of documents and submit applications to selected providers. Apply in parallel to a traditional lender and a digital provider to reduce timing risk.
Book meetings early. Appointment lead times commonly stretch one to four weeks. Keep travel flexible if an in‑person interview is required.
What happens in the interview and typical questions
Bring originals and a short business summary. Expect questions about customers, suppliers, countries of operation, expected volumes and source of funds.
Tip: keep answers factual and tied to documents so reviewers do not need follow-up verification.
Internal checks: KYC, AML, UBO and risk profiling
After the interview, the provider runs identity checks, AML screening and UBO verification. Risk profiling assesses industry, transaction patterns and counterparty countries.
Decisions usually occur after internal review, not at the meeting. Clear, consistent paperwork makes that review faster.
Responding to clarification requests
Reply quickly, attach the exact supporting file referenced and avoid changing key details across forms. Precise responses cut re‑review cycles and speed approval.
“A prompt, documented reply is the single best tool to reduce processing time.”
| Stage | Business action | Provider action |
|---|---|---|
| Submission | Send consistent documents; apply to multiple providers | Log application; schedule interview |
| Interview | Attend with originals; present business summary | Sight documents; record notes |
| Internal review | Stand ready to answer clarifications | Run KYC/AML/UBO and risk assessment |
| Approval | Complete activation steps and initial deposit | Issue formal approval and setup access |
What causes delays or rejection and how to fix issues before applying
Applications often stall because submitted paperwork does not match the business narrative.
Unclear business model or inconsistent documentation
Vague descriptions force extra due diligence. Provide a one-page summary that states products, customers, typical invoice sizes and payment corridors.
Attach real invoices, screenshots and signed proposals so every claim is verifiable.
Weak operational substance and virtual office red flags
Virtual addresses alone look risky. Supply a lease, serviced office agreement or proof of occupancy and staff presence to show genuine operations.
High-risk activities without licences
If your model touches regulated sectors—payments or crypto—obtain licences or formal approvals before applying to traditional providers.
Non-resident director complications
When control sits offshore, banks expect extra context. Provide board minutes, local contact details and clear ownership charts to reduce follow-ups.
Unverifiable source of initial capital
Trace the initial funds with historic bank statements, loan agreements or investor wires. Reconcile the amounts with projected volumes to speed approval.
- Quick fix: audit all documents for consistent names, dates and addresses before submission.
- Checklist: business narrative, operational proof, licences, director evidence, financial trail.
For legal and service terms that affect documentation standards, review our terms and conditions.
How to shorten the timeline and improve approval odds for foreign-owned companies
A focused plan that prevents rework will speed approvals more than rushed requests to compliance teams.
Apply in parallel to multiple providers
Submit applications to a mix of traditional banks and fast fintechs. This reduces single‑point delay risk and gives you options if one provider asks for extra checks.
Build transparent source-of-wealth files
Provide a clear documentary trail showing how funds were accumulated. Use dated statements, sale agreements or investor transfers and tie them to the initial deposit.
Label each file so reviewers can match evidence to claims quickly. That cuts repeated clarifications.
Practical governance and balance signals
Consider appointing a resident director where it materially improves governance comfort. A local director often reduces perceived control risk and speeds local reviews.
Keep an appropriate initial deposit and stable balances. Early volatility or zero balances can trigger immediate questions about projected volumes or services.
Speed‑up plan and timeline discipline
Start early and allow at least six to eight weeks in planning. Track each milestone and assign a single contact to answer clarifications fast.
“A small, consistent document pack and one responsive contact cut re‑review cycles dramatically.”
| Action | What to prepare | Impact |
|---|---|---|
| Parallel applications | Pack for two providers (traditional + fintech) | Reduces single‑provider delay |
| Source-of-wealth | Statements, contracts, wire traces | Fewer compliance queries |
| Resident director | Local contact details + minutes | Improves governance comfort |
| Initial funds | Minimum deposit and stable balance | Signals operational stability |
Final tip: assume a multi‑week window, keep answers timely and maintain consistency across all forms to increase the chance of swift approval.
After approval: account activation, early monitoring, and compliant operations
After approval, teams should focus immediately on activation steps and early operational controls.
Setting up internet banking, signatories, and corporate cards
Practical checklist: enable online access, configure multi‑user signatory rules, request corporate cards and set payment rails needed for regular operations.
Assign roles and test login credentials. Ensure signatory limits match internal governance and authorisation workflows.
Understanding early monitoring periods and potential transaction limits
Expect an early monitoring window of roughly 3–6 months. During this time, banks often apply tighter transaction thresholds and closer scrutiny.
Reviewers compare real activity to declared volumes and corridors. Sudden spikes or unfamiliar corridors can prompt extra checks or temporary limits.
Keeping transactions aligned with declared business activities
Keep actual transactions consistent with your business activities. If your model or counterparty countries change, notify the bank promptly and provide updated documentation.
Record-keeping expectations and operational controls
Maintain invoices, contracts, receipts and statements in a searchable system. Most banks expect at least five years of records for audits and periodic reviews.
- Set approval workflows, reconciliation routines and centralised storage.
- Label files clearly to speed responses to clarification requests.
- Monitor liquidity and avoid unexplained volume changes.
“Consistent operations and clear records reduce re‑reviews and keep services stable.”
| Action | What to prepare | Expected outcome |
|---|---|---|
| Online access | Admin user, MFA, roles | Secure day‑to‑day operations |
| Early monitoring | Projected volumes, counterparty list | Fewer queries; higher limits sooner |
| Record keeping | Invoices, contracts, 5 years of statements | Audit readiness and regulatory compliance |
When professional corporate services can help with bank account opening
Professional advisers streamline complex requests and raise the chance of smooth, timely approvals. They are most useful when founders are new to local procedures, ownership is layered, regulated activities are involved, or deadlines are tight.
Bank selection, introductions and appointment support
Advisors map your business profile to institutional appetites. They recommend providers that fit your industry, ownership and expected transaction patterns.
They also arrange introductions and coordinate meetings to reduce scheduling gaps and travel risk.
Preparing bank-ready documentation and compliance narratives
Experts assemble consistent packs and craft a concise compliance narrative that answers likely questions upfront.
Result: fewer follow-ups and a cleaner internal review.
Managing follow-ups, clarifications and resubmissions
Professionals act as a single point of contact, submitting clear replies and the exact supporting documents requested. That minimises resubmissions and keeps applications moving.
Note: third-party help improves quality and speed but cannot reverse an institution’s independent risk decision.
For a deeper practical guide on corporate bank account options, see our corporate bank account guide.
Conclusion
A structured plan that maps paperwork to reviews turns an uncertain process into a predictable one.
Treat the search for a bank account as a compliance project with clear stages: incorporate and secure your UEN, prepare consistent documents, apply and attend the interview, complete internal review, then activate services.
Expect a practical window of about 4–8 weeks with traditional providers. Build buffer time to protect cashflow and continuity. Consider a digital bank account to move funds quickly, then add a corporate bank account relationship for broader services as the business scales.
Action checklist: prepare a one‑page business summary, align names and addresses across files, document source of funds, and respond promptly to queries. Use this guide as an ongoing reference to stay compliant after approval.
FAQ
What is the usual end-to-end approval window for a foreign-owned corporate bank account in Singapore?
Why do enhanced AML and KYC checks extend processing times for foreign entities?
What incorporation steps must be completed before applying?
Which corporate documents do banks request most often?
What identity and address proofs are required for directors and ultimate owners?
When do I need apostilles or consular legalisation for overseas documents?
How should non‑English documents be handled?
Do banks require a local representative or resident director?
What evidence of business activities should I prepare?
What financial disclosures do banks usually ask for?
How long do appointment wait times at traditional institutions typically take?
Can I complete the process remotely or do I need to travel to Singapore?
What are common reasons for delays or rejection and how can I avoid them?
How can I shorten the overall process and improve approval chances?
What should a one‑page business summary include to reduce follow-up queries?
What happens immediately after approval and what monitoring should I expect?
Which account types suit multi‑currency operations and international trade?
What administrative steps speed up review, such as using CorpPass?
When should I engage professional corporate services?
Are there typical fees, minimum deposits or balance requirements I should compare?

Dean Cheong is a Singapore-based commercial growth architect and CEO of VOffice, known for helping B2B companies turn fragmented sales efforts into predictable revenue systems. He specializes in sales process optimisation, CRM-driven visibility, and market entry strategy, combining execution discipline with a strong academic grounding in business banking and finance from Nanyang Technological University. His focus is on building repeatable, data-backed growth frameworks that companies can scale with confidence.